JMMB pension experts urge household workers to prioritise retirement planning

/ Our Today
administrator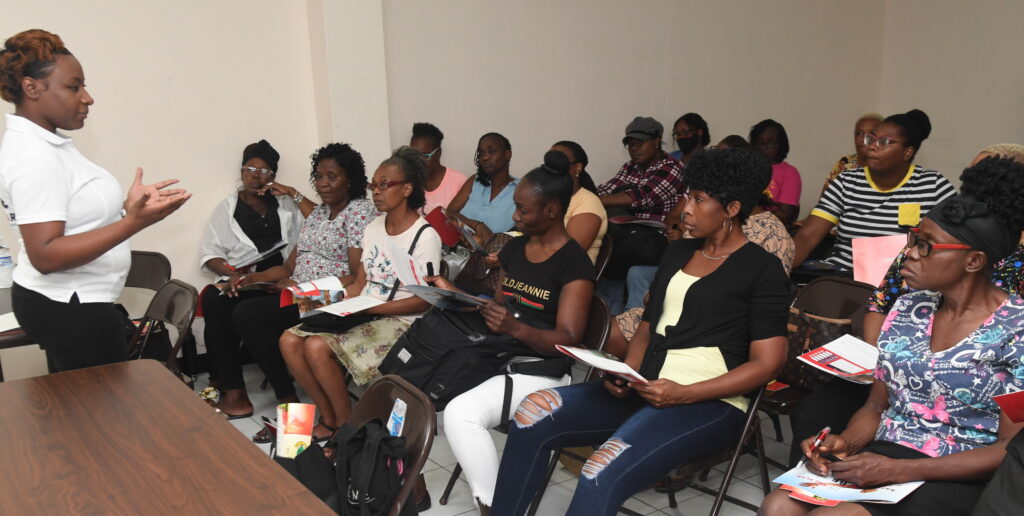
JMMB’s pension experts urged the all-female audience of household workers to make retirement planning a top priority, while speaking at a recent session at the Jamaica Household Workers’ Union (JHWU) headquarters.
Camille Steer, senior corporate manager of JMMB Fund Managers, underscored the urgency of retirement planning, highlighting the plight of many elderly individuals whose time in the workforce was extended due to the need to meet their basic needs. She shared that this unfortunate reality is commonplace in Jamaica, as less than 20 per cent of the workforce are members of an approved pension arrangement.
NIS contributions: First layer of retirement planning
Taneka Lawrence, fund sales & service officer at JMMB Fund Managers outlined the first layer of one’s retirement plan is to contribute to the National Insurance Scheme (NIS), which is established by the government as a part of the social safety net.
It offers individuals and their families, varied benefits such as maternity benefit, injury on the job, incapacity, pensioner’s health insurance, special child benefit, funeral grant, orphan benefit and death benefit.
With a minimum of 10 years’ contributions, members can get a consistent income from NIS during retirement, in addition to accessing other benefits. Lawrence admitted that even though this is a key ingredient in one’s retirement plan, it is unlikely to maintain one’s preferred lifestyle with only this in place as the current minimum NIS pension payment is approximately J$4,200 per week.
‘Be SMART’
To fill this financial gap, individuals should have a smart goal to help guide their retirement planning.
Collette Walker, fund sales administration officer, explains that this means, “getting to know your numbers,” so that you have a specific saving and investment target for retirement.
A retirement calculator that is available through several financial institutions’ websites, such as JMMB, in conjunction with speaking with a licensed financial advisor helps provide an approximate projection.
Creating Your ABC Plan
Outlining the steps to create one’s retirement plan Camille Steer, shared the acronym – ABC – audit your finances; budget; and consistently contribute.
Audit your finances: Setting a SMART goal for your retirement forms the foundation for auditing your finances as this serves as a blueprint along your financial journey to understanding your income vs expenses, investments and savings. She adds, “At retirement, it is recommended that you have at least 75 per cent of your last pay cheque, however, based on the lifestyle you want to live you may need more.”
Create a budget: Camille encouraged having a written monthly or weekly budget to keep track of expenses, and as best as possible live within your means so that you can maximise your earnings. “Tracking your expenses (is like) your ‘financial self-care’, where you set aside time to review your budget and make adjustments as is necessary to maintain a good financial routine.”
Acknowledging that earnings may seem limited with the high cost of living, she advised that careful planning is the key. Having an emergency fund is important to navigate financial hardships and ensure that your long-term goals like retirement remain on track and start building wealth by investing. “Do not be deterred if you have not been investing, instead become financially educated and rely on the expertise of your advisor (for guidance),” Steer said. Adding, “You do not have to invest in every investment opportunity, only the ones that suit you and your needs.”
Note that unit trusts can be a good entry point as they require limited funds to invest and are typically managed by experts while giving stable returns.
Consistently contribute: “Consistency is your superpower,” advised Steer. “The big money is important but even more important is consistency as this provides you with the opportunity for compound interest, which is a game changer.”
Steer encouraged the attendees not to lose hope in the face of challenges, and to overcome negative self-talk by focusing on their financial resilience and options to supplement their income.
Dispelling any anxiety about ‘defaulting on retirement contributions’, the pension expert shared that although consistency is key, your retirement plan can be flexible, whereby you are not penalised for missing a monthly payment; as ‘life happens’. However, reducing or taking a break from making your pension contributions should only be done in dire circumstances, as it will ultimately affect your ability to be set for life.
Now is better than never
“Don’t be disheartened if you have not started on your retirement journey, it is never too late, the best time to start is now,” Steer consoled the ‘late bloomers’, over 50. Sharing pointers to get these individuals on track Camille noted that now is the time to get laser-focused and redouble efforts towards their retirement goal. The first step she said was to consult your advisor so you can determine your projected target amount for retirement, start investing or review and update your retirement portfolio if it was neglected.
Camille explained that during one’s retirement years, a monthly payment is paid by an insurance company based on your cumulative pension contribution, known as an annuity. You should know your projected monthly payment, from your retirement provider so that you can make adjustments to your retirement contributions, extend retirement to 70 years old, health permitting or explore additional sources of income such as renting a section of a home, insurance policies or other skills to generate savings.
For persons who may be over the normal retirement age of 60 years, she admitted that although it is not an ideal situation all is not lost. A key component at this stage is to diversify your investments to maximise returns. Additionally, even if you do not qualify to receive pension payments from NIS due to insufficient contributions, you may qualify for a one-off grant.
Retirement planning is an ongoing journey, whatever your age, stage or income, therefore persons should monitor and measure their progress against the adequacy of the projected amount for their retirement. Noting, that if you recognise that you are off-track, this requires that you rebalance your finances to match your current reality and take deliberate steps to get back on target.
Comments