The back-to-school expense parents cannot afford to overlook

/ Our Today
administrator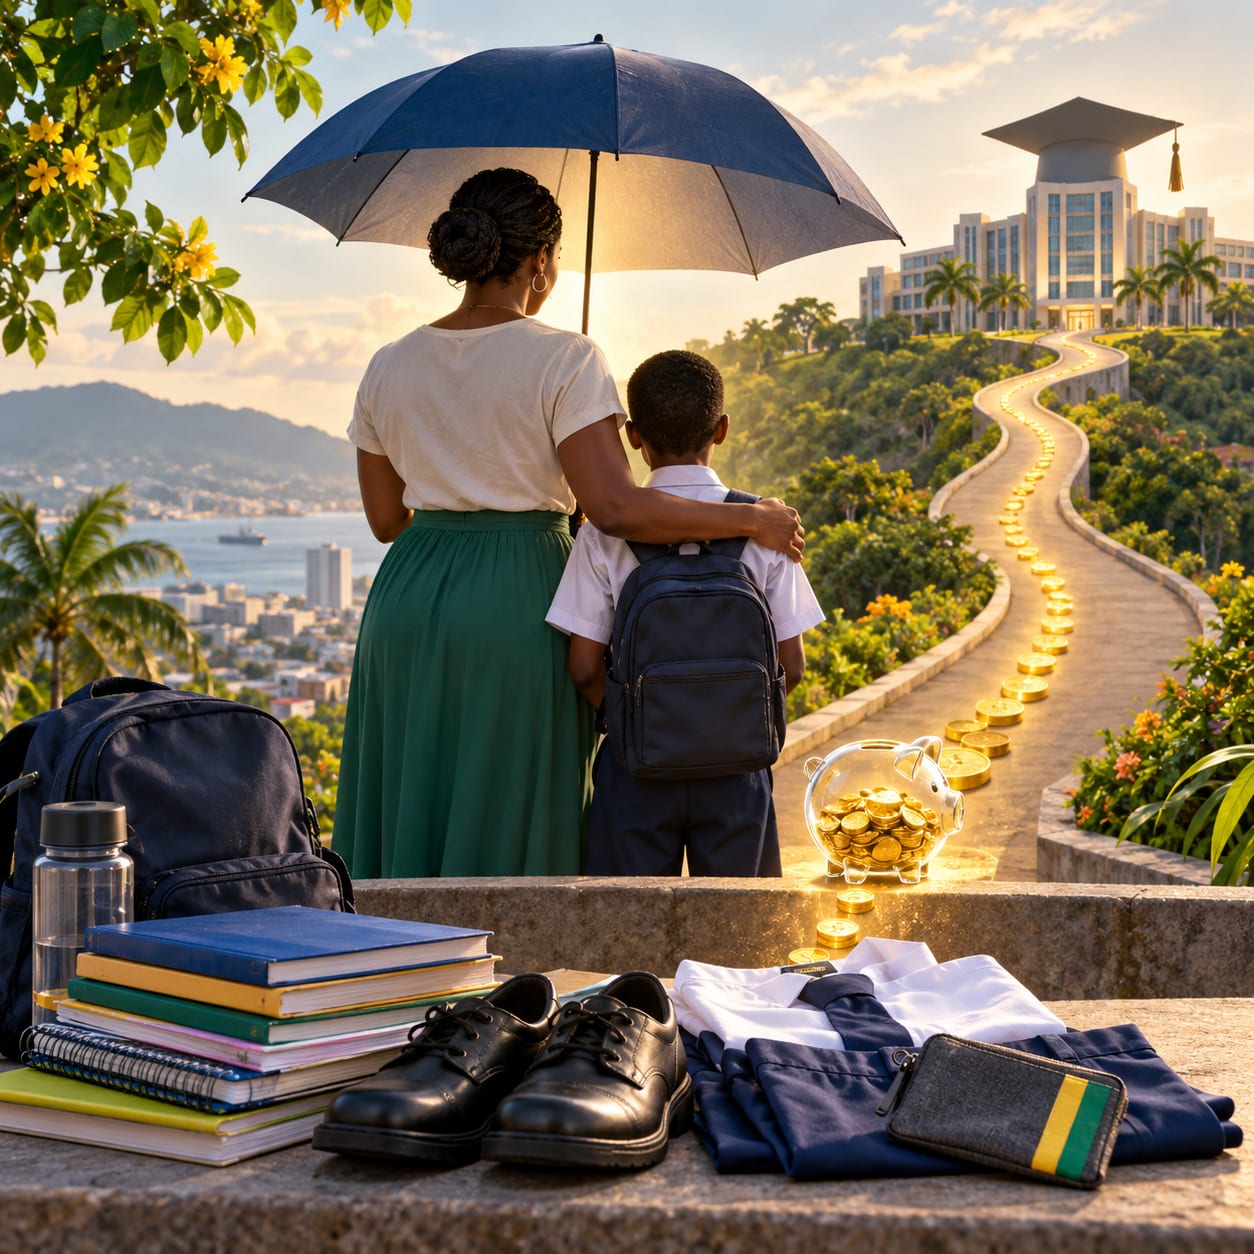
Parents may be focused on uniforms, books and transportation as the new school year begins, but the most consequential cost could be the one that still feels years away. Planning early for tertiary education, while protecting the income that supports a child, can prevent families from facing a much larger financial burden later.
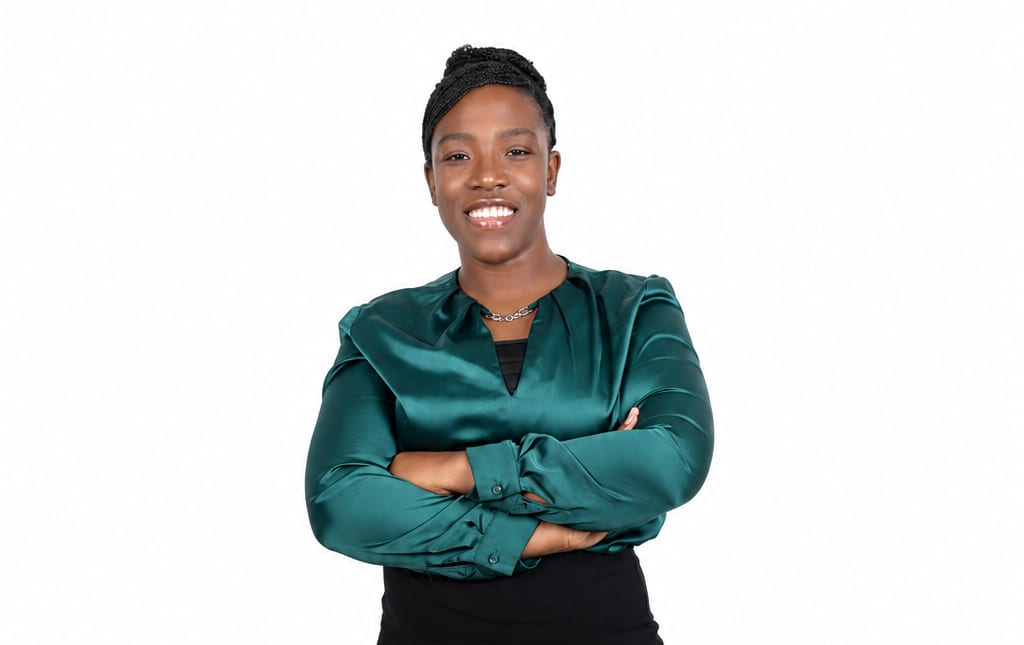
The good news, according to Jheanel Dixon, Sagicor Life Jamaica’s Financial Advisor of the Year, is that parents do not need a large sum to begin. A modest amount saved consistently, guided by a clear goal, can make the future more manageable.
Dixon, who is also a mother, said a complete plan should look beyond today’s school fees and uniforms to future expenses such as tuition, books, transportation, accommodation, technology and healthcare. The earlier parents identify those costs and the time available to prepare, the more options they are likely to have.
“The aim is not to add pressure when parents are already carrying significant responsibilities. It is to start with what is manageable, set a clear goal and build consistently. Waiting until a child is older can mean having to find significantly more money in a much shorter period,” Dixon said.
Saving is only half the plan
She recommended keeping money for a child’s future separate from general household and emergency funds where possible. A dedicated fund makes progress easier to track and less likely to be absorbed by other expenses. But savings are only one part of the plan; parents should also review their insurance coverage.
“A child’s financial security depends heavily on the parent or guardian providing for them. If illness, disability or death interrupts that income, education and other essential needs may be affected. Protecting the parent is therefore part of protecting the child,” she said.
This is especially important for single-income households. Parents should consider whether existing arrangements would cover household expenses, debt, childcare and education if their ability to earn changed unexpectedly.

Dixon also advised parents to keep beneficiary information current and revisit savings and insurance arrangements after major life changes, including the birth of another child, a change in employment or income, marriage or separation.
Her message to parents is simple: do not wait for the perfect amount or the perfect time. “Start with a clear purpose and an amount you can sustain. Small, consistent steps can make a meaningful difference, and the plan can grow as the family’s circumstances and the child’s needs change,” Dixon said.
Comments