Ambraee Houslin | What the listed consumer complex is telling us about the Jamaican household

/ Our Today
administrator
The listed consumer names are the highest-frequency instrument we have for reading the Jamaican household. Quarterly national accounts arrive with a lag and are revised. The consumer price index tells us what things cost, not what people bought. The companies that sell food, drink, pharmacy goods and hotel supplies transact with the same households every week and report every quarter, and their numbers carry information that no macro release does. A year on from Hurricane Melissa, that information is worth reading carefully, because the market appears to have made up its mind about the recovery well ahead of the evidence.
Start with the aggregate. On the third-party sector screens, the Jamaican consumer staples complex entered April 2026 with roughly J$350 billion of market capitalisation against a pooled earnings base of about J$20.2 billion. Eight months earlier, that same earnings pool sat near J$26 billion. Market value barely moved over the interval. Prices, in other words, fell by far less than earnings did, and the sector’s price-to-earnings multiple widened to something in the region of 17 times against a three-year average closer to 12. That is not a market pricing distress. That is a market that has decided the earnings hit was a one-off and that the pre-storm profit pool returns intact.
It may be right. It is worth being clear about what has to happen for it to be right, because the recovery being priced requires two separate things in the same year: volumes have to come back, and margins have to come back with them. Those are not the same recovery and they do not have the same probability. Volume recovery follows from reconstruction, tourism and remittances, all of which are moving in the right direction. Margin recovery requires input costs, freight and energy to stop rising while pricing power holds, in an economy where headline inflation reached 7.5 per cent in July, core inflation reached 5.2 per cent, and the central bank has chosen to hold the policy rate at 5.5 per cent rather than lean against the pass-through. The distribution of outcomes here is not symmetric.
The dispersion within the complex is more instructive than the aggregate. Wisynco went through the storm quarter with consolidated revenue up 14 per cent to J$16.19 billion and gross profit up 27 per cent to J$5.92 billion, despite hotels and food service closing in the west. It absorbed the shock because it had spent something over J$5 billion across roughly three years on capacity, product breadth and distribution depth, and because when one channel closed it moved volume through the others. GraceKennedy reported an 18 per cent rise in June quarter profit to J$2.4 billion on revenue growth of 6.26 per cent. The tourism-facing and pure retail names did not fare that way, and the share prices show it. Over the twelve months to the late winter, Caribbean Producers was down about 24 per cent, Lasco Distributors about 27 per cent, Fontana about 16 per cent, Dolphin Cove about 23 per cent and Supreme Ventures about 12 per cent, with Dolphin Cove and Supreme Ventures both deteriorating further into the spring.
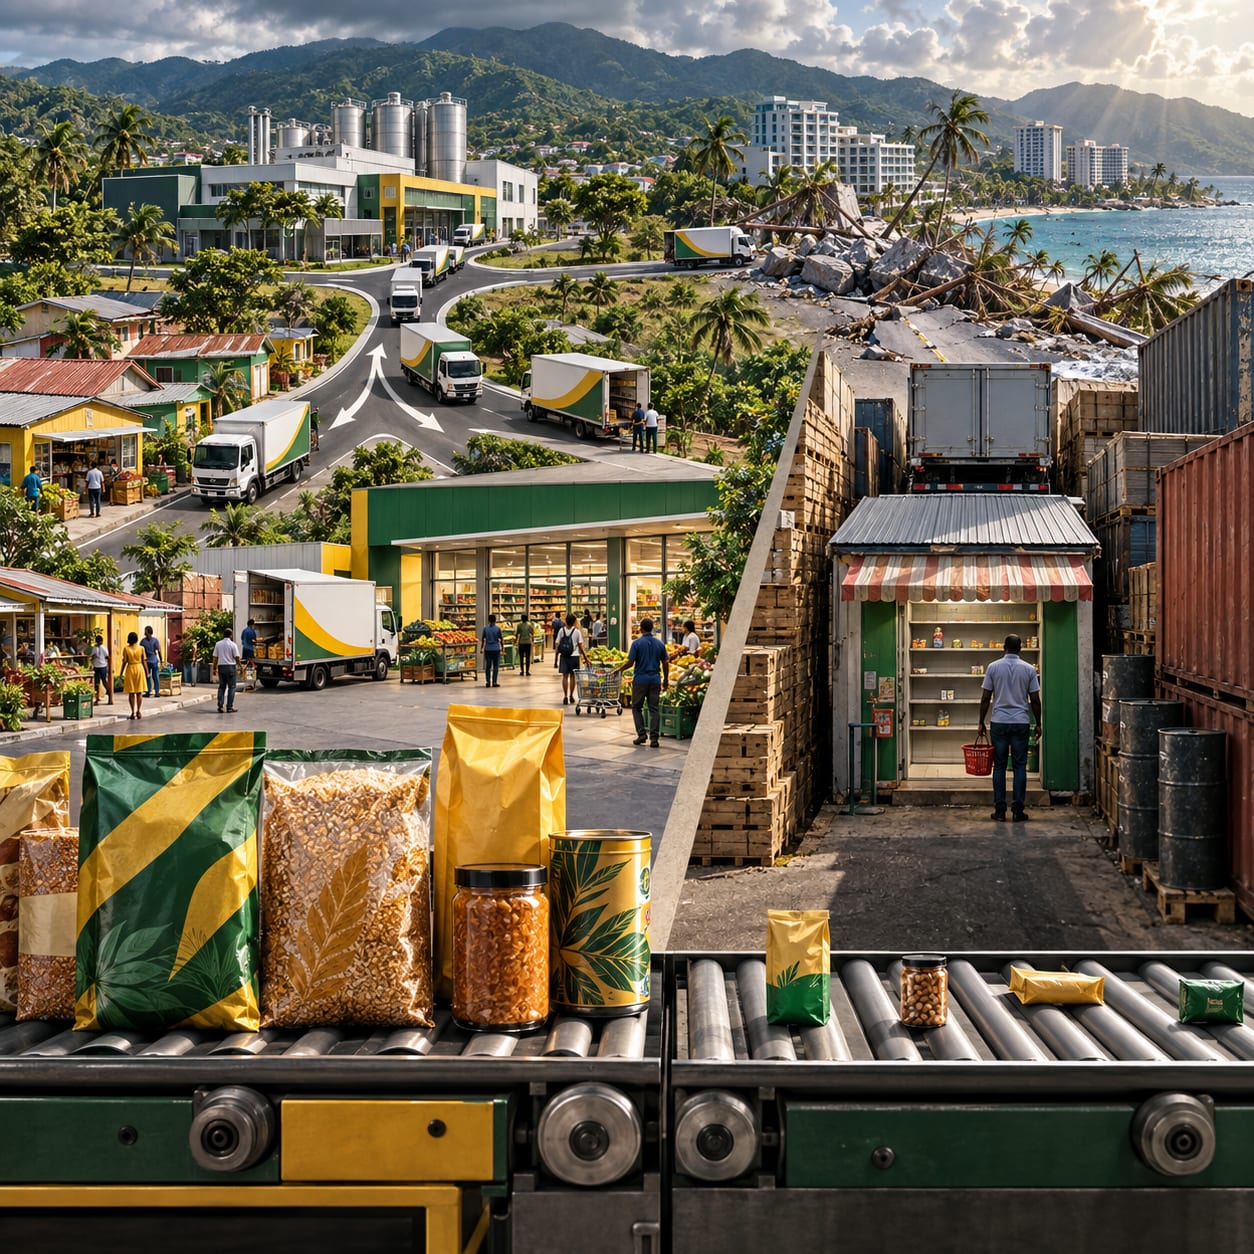
That dispersion has a single organising principle, and it is not brand strength or shelf position. The firms that held up own their manufacturing capacity and their route to market. They set their own prices, and they decide which channel takes the volume. The firms that suffered sit downstream, buying at prices they do not set and selling into a channel they do not control, which in the case of the hotel supply chain was closed for part of the period. In a year that combined a volume shock with a cost shock, the entire outcome was determined by where a company sat in the value chain. That is a durable lesson rather than a storm anecdote, and anyone underwriting Jamaican consumer risk, as an equity investor or as a lender, should treat it as the discriminating variable.
There is a caution buried in almost every top line in the sector, and local commentary keeps walking past it. Nominal revenue growth below the rate of inflation is a volume decline. GraceKennedy’s 6.26 per cent revenue growth in the June quarter sits below the 7.5 per cent headline print for July. Massy’s seven per cent group revenue increase over nine months sits in the same territory. These are not necessarily bad results, and in the case of both companies the profit performance was creditable, but reporting them as growth without deflating them describes price rather than demand. A sector that raises prices seven per cent and reports six per cent more revenue has sold fewer goods. If we are trying to read the household, that distinction is the whole exercise.
The clearest signal in the set came from a company that decided to leave. Massy Holdings completed the sale of Massy Distribution (Jamaica) in March, crystallising a translation loss of TT$105.3 million, more than J$2.3 billion, and keeping its Jamaican gas and technology businesses. The chairman framed it as concentrating capital where the group is best positioned to earn attractive long-term returns, and the loss itself was an accounting consequence of recycling accumulated currency translation rather than a cash outflow or a judgement on the operating business. All of that is true, and none of it changes what the decision was. A disciplined regional allocator with a century of Caribbean operating history examined Jamaican consumer distribution, compared it with alternative uses of the same capital in Guyana, Trinidad and Colombia, and redeployed. In its nine-month results, the group reported growth in gas products in Trinidad and Guyana, offsetting softer performance in Jamaica after the hurricane. The Jamaican market has treated the disposal as a piece of accounting news. It is better read as a verdict from a well-informed outsider, and it deserves an answer rather than a shrug.
One further indicator is worth adding to the dashboard because almost nobody watches it. Radio Jamaica reported group revenue down 23.8 per cent in a single quarter, driven principally by advertising, with nine-month revenue down about 12 per cent and after-tax losses widening substantially. Advertising is the first line a firm cuts and the last it restores, which makes it a cleaner read on what companies expect households to spend than any staples revenue line, because staples revenue is inflated by price and advertising budgets are not. When the people who sell to consumers stop paying to reach them, they are telling you something about their own forecasts.

So where does that leave the next four quarters? Reconstruction spending is real, but it is an income transfer into construction, hardware and building materials rather than into food retail, and it flows to a specific geography and a specific set of trades. Remittances are running modestly ahead, with inflows of US$542 million in the first two months of the year, about 4.2 per cent up on the prior year and equivalent to something in the region of 15 per cent of national income, which is close to flat once United States price levels are taken into account. Tourism has recovered on arrivals, with 2.34 million visitors and about US$2.5 billion in earnings in the eight months to 31 August, which supports the hotel supply chain and the names levered to it. Set against a fiscal year in which real output is estimated to have fallen around 4.5 per cent, with accommodation and food services down 31 per cent and agriculture down 17.7 per cent in the December quarter alone, the recovery arithmetic is demanding rather than impossible.
The useful question for an investor is therefore not whether the Jamaican consumer recovers. On the evidence, some version of recovery is already under way. The question is who captures it, and the last twelve months have answered that with unusual clarity. Capacity, pricing power and control of distribution determined who made money through the shock, and there is no reason those advantages evaporate when conditions normalise. A market paying 17 times for a consumer earnings pool that has shrunk by roughly a fifth is paying for the average outcome in a sector where the outcomes have not been remotely average. The names that earned their multiple through the worst of it are not the ones trading at a discount, which is precisely the problem with buying the sector rather than the company.
Ambraee Houslin is a private equity strategist with a strong background in economics and statistics. He has extensive experience in investment banking, corporate finance, and investment research across Jamaica and the Caribbean region. His core expertise includes mergers and acquisitions, capital structuring, and executing complex transactions that drive growth and value creation. Ambraee has led and supported deals spanning strategic acquisitions, private credit facilities, and post-transaction integration strategies for high-impact sectors.
Comments