Douglas Levermore | Micro Lending, Macro Impact

/ Our Today
administrator
Somewhere this morning, a woman will borrow what a commercial bank might consider an almost laughably small amount of money.
She may use it to purchase additional inventory for a roadside shop, buy a sewing machine, acquire two goats, expand a food stall or purchase equipment for a small beauty business. There will be no ribbon-cutting ceremony, no investment banker, no glossy prospectus and certainly no financial journalist waiting outside.
Yet that modest transaction may help feed a family, pay school expenses, support another supplier, create employment and introduce another citizen to the formal financial system. That is the quiet genius of microfinance. The loan may be micro. The economic consequences can be anything but.
Traditional banking was built largely around a sensible proposition: before lending money, determine whether the borrower can repay it. The difficulty comes when the mechanisms used to answer that question automatically exclude millions of people. No payslip. No audited financial statements. No conventional collateral. No long credit history. No loan. The irony is that a person can operate the same small business successfully for fifteen years and still appear practically invisible when viewed through the window of a traditional credit department.
Microfinance challenged that thinking. Its great innovation was not simply lending smaller amounts of money. It was recognising that lack of collateral is not necessarily lack of character, and lack of a banking history is not necessarily lack of creditworthiness. Institutions learned to assess borrowers differently—through cash flow, community knowledge, group structures, repayment behaviour and progressively larger loans. In effect, microfinance began lending to people whom the legacy banking system often did not know how to evaluate.
Bangladesh remains the obvious place to begin. Institutions such as Grameen Bank, BRAC and ASA helped transform microcredit from an interesting development experiment into a global financial movement. Bangladesh’s experience has not been flawless, and the industry has had to confront questions about multiple borrowing, consumer protection and excessive indebtedness. Indeed, the sector deliberately moderated its expansion when warning signs emerged. But that may itself be one of the lessons: a mature microfinance system must know that lending more money is not necessarily the same thing as creating more development.
India has similarly developed microfinance on an extraordinary scale, while Kenya has demonstrated how small-scale finance can be combined with technological innovation and mobile financial services. Peru provides another fascinating example. Its microfinance ecosystem developed a broad range of specialised institutions serving households and microenterprises that conventional banks historically struggled to reach. At one stage, the World Bank Group’s IFC described Peru as having been ranked first for five consecutive years in an international assessment of the enabling environment for microfinance.
What makes these systems economically interesting is what happens after the money leaves the lender’s hands.
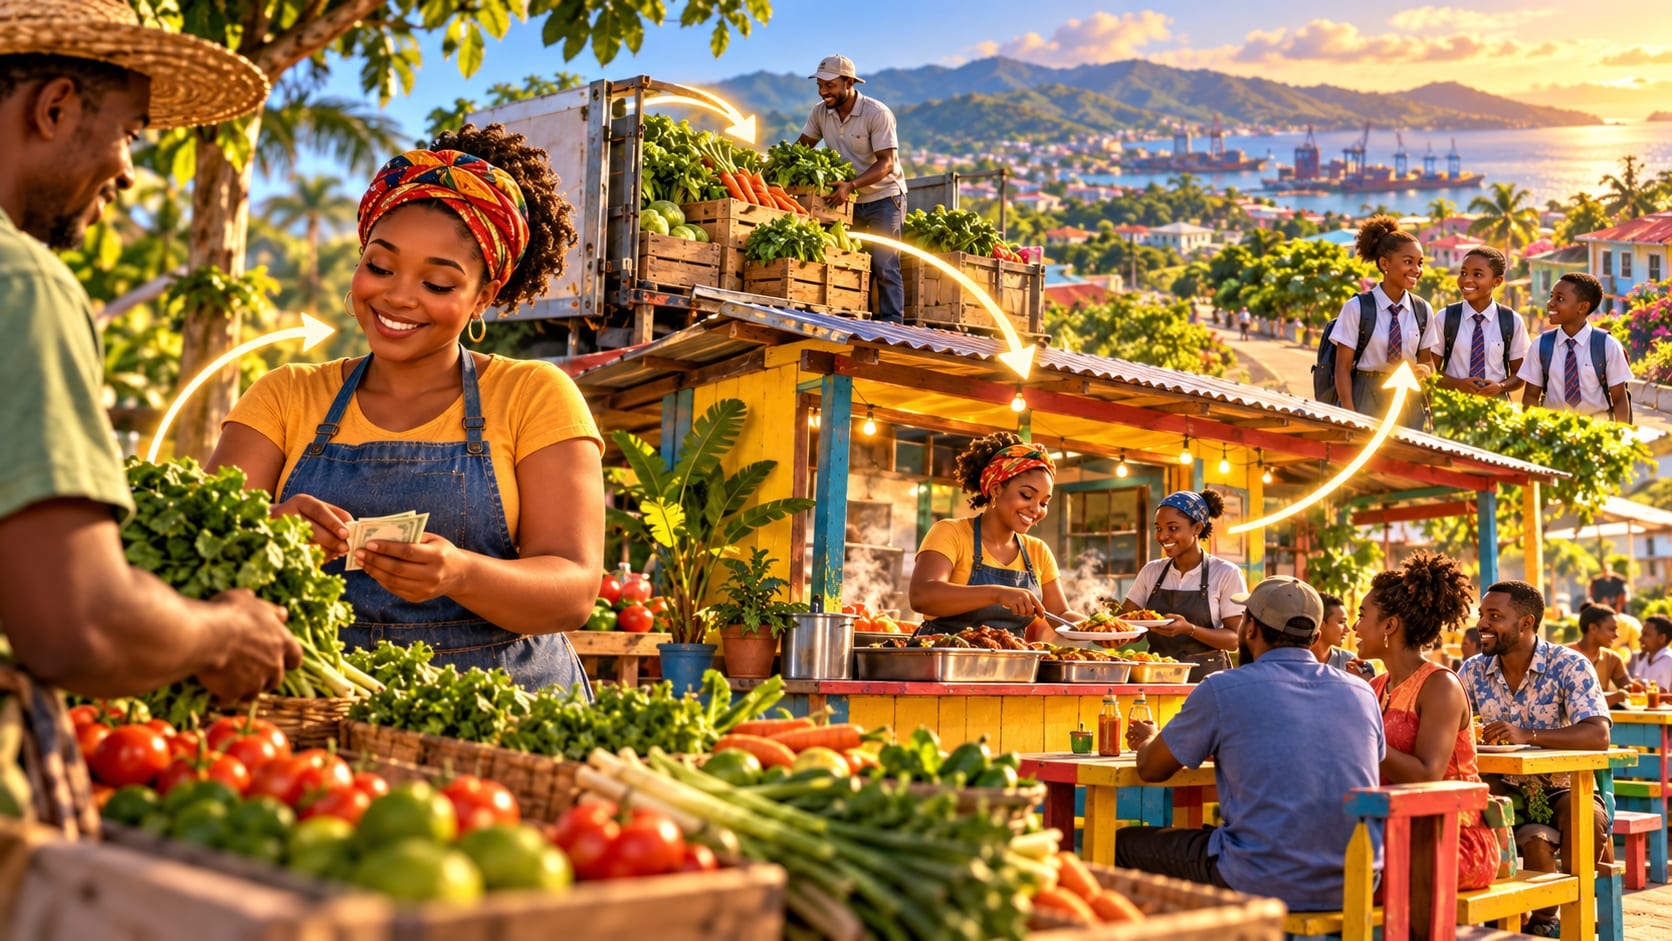
Consider the woman who borrows $500 to expand a small food business. She buys produce from a farmer, containers from a wholesaler and cooking gas from a distributor. Increased sales may require somebody to help prepare the food. Her additional income pays transportation costs, electricity bills and school expenses. Perhaps she eventually buys a refrigerator from a local appliance store. The refrigerator distributor orders another unit. Somewhere along that chain, taxes are collected.
Economists call these linkages and multiplier effects. Ordinary people simply call it business.
This is why measuring microfinance exclusively by the size of the original loan misses much of the story. The important question is not merely: How much was borrowed? It is also: What economic activity did that money unlock?
Research provides reasons for both optimism and humility. Randomised studies have generally found that conventional microcredit is not the miraculous poverty-eradication machine that some early advocates imagined. A synthesis of seven randomised experiments concluded that average effects on household businesses and consumption were unlikely to be transformative. Research in India similarly found increased investment in existing businesses without broad improvements across every measure of household welfare.
But that is hardly an argument for abandoning microfinance. It is an argument for understanding what the instrument actually does well.
In Mongolia, for example, researchers found that group-based microcredit increased female entrepreneurship and household food consumption. Research on savings-led microfinance groups in Ghana, Malawi and Uganda found improvements in household business outcomes and women’s empowerment, although not in average consumption. More recent work examining flexible credit structures suggests that appropriately designed repayment terms can improve business performance considerably.
In other words, perhaps microfinance was burdened by an unreasonable expectation. A $700 loan should not be expected to accomplish what governments, education systems, healthcare systems and labour markets have struggled for generations to achieve. Credit cannot single-handedly eliminate poverty. What it can do is remove one important obstacle: the inability of a capable person to obtain productive capital simply because he or she is poor.
Then there is repayment: One of the most fascinating features of successful microfinance has historically been the repayment discipline achieved among borrowers whom conventional financial institutions might classify as risky. Group accountability, frequent contact with loan officers, progressively larger borrowing opportunities and the importance borrowers attach to maintaining access to credit can create powerful repayment incentives.
However, comparisons with commercial banks require care. Microfinance institutions commonly report Portfolio at Risk over 30 days (PAR30), while banking systems frequently classify loans as non-performing at 90 days or according to other regulatory criteria. They are not the same measurement. The World Bank itself cautions that differences in national accounting and supervisory practices complicate cross-country comparisons.
It would be tempting to proclaim that poor microfinance borrowers universally repay better than wealthy bank customers. The evidence does not justify such a sweeping conclusion. Microfinance portfolios can deteriorate badly during economic crises; the pandemic demonstrated precisely that. The Consultative Group to Assist the Poor’s analysis found significant increases in credit risk during COVID-19, and its more recent work indicates that portions of the sector remain vulnerable.
Yet something important remains: millions of low-income borrowers have demonstrated repeatedly that poverty should not automatically be treated as a synonym for irresponsibility.
ˇhis is the lesson that traditional banking should study most carefully.
Legacy banking asks, quite reasonably, “What assets does this person have?” Microfinance added another question: “What can this person do if given access to capital?” Those are fundamentally different ways of looking at human economic potential.
There is another downstream benefit that receives insufficient attention. A well-managed microfinance relationship can become a financial graduation ladder. Today’s $300 borrower may become tomorrow’s $1,500 borrower, then a $10,000 small-business customer, a depositor, an insurance customer and eventually the owner of an enterprise employing several people. The objective should therefore not be to keep customers permanently in microfinance. Success should sometimes mean helping them outgrow it.
That requires responsible lending. There is nothing socially noble about burying a poor household beneath expensive debt. Interest rates must be transparent. Collection practices must preserve dignity. Regulators must watch multiple borrowing. Credit bureaus should increasingly include microfinance borrowers so that good repayment behaviour becomes a portable financial asset. Financial literacy should accompany financial access. And digital technology should reduce transaction costs rather than merely make it easier to push another loan onto somebody’s telephone.
There is also a lesson here for governments across the developing world, including the Caribbean. Policymakers often speak enthusiastically about entrepreneurship while financial systems remain disproportionately comfortable lending against established salaries, property and conventional collateral. Yet some of tomorrow’s most productive businesses are presently operating from kitchens, verandas, market stalls, small farms, barbershops and spare bedrooms.
They may not need a million dollars.
They may need $2,000—and somebody willing to believe that $2,000 matters.
Microfinance at its best is therefore not charity. Charity gives because someone has a need. Finance lends because someone has potential and a reasonable capacity to repay. That distinction is enormously important because dignity is preserved when people are treated not simply as beneficiaries of development but as participants in it.
The world should resist romanticising microfinance. It will not eliminate poverty by itself; every microenterprise will not become a corporation, and irresponsible lending can create precisely the hardship financial inclusion is supposed to prevent. But neither should policymakers underestimate what happens when millions of economically invisible people are finally given access to appropriately designed financial services.
Jamaica’s experience with microfinance offers an instructive reminder that people with modest incomes should not automatically be confused with people who are poor credit risks. Many microfinance customers take their repayment obligations extremely seriously, understanding that a record of paying reliably—and, in some cases, paying ahead of schedule—is the passport to the next loan when school fees, inventory, a refrigerator, a small-business opportunity or an unexpected family expense arises. The scale of the Jamaican market itself tells part of the story. The Bank of Jamaica reported that by the end of 2025 it had licensed 112 microcredit institutions, representing approximately 99 per cent of the sector’s assets, while applications received since 2021 represented some J$46.1 billion in aggregate loans. More recent Jamaican risk-assessment data put the number of microcredit customers at 75,741 in 2024 and reported that approximately 95 per cent of clients were classified as low or medium risk during 2022–2024. Those figures do not mean that every borrower pays perfectly—defaults and delinquency remain genuine challenges in the industry—but they do challenge the lazy assumption that a small borrower is necessarily an unreliable borrower.
Indeed, one of microfinance’s most important contributions may be that it allows an ordinary Jamaican without substantial collateral to demonstrate something that a conventional balance sheet cannot easily capture: character expressed through repayment behaviour. Jamaica’s credit-reporting system records whether accounts are current or past due, and the Bank of Jamaica explicitly notes that borrowers with good credit histories can benefit because lenders are better able to assess their creditworthiness and price risk accordingly. For the market vendor, hairdresser, taxi operator, small farmer, shopkeeper or salaried worker borrowing a relatively modest sum, therefore, paying on time is not merely settling this month’s obligation; it is building a financial reputation. That may be one of the quiet successes of microfinance: it converts the discipline of the small borrower into evidence that the formal financial system can eventually see.
One tiny loan purchases inventory. The inventory generates sales. Sales generate income. Income supports a household. The business purchases from another business. Eventually somebody is hired. A repayment record is established. Savings accumulate. Another loan becomes possible.
And somewhere along that chain, a person who once stood outside the financial system begins building a financial history of his or her own.
That is why the most important word in microfinance may not be micro.
Because when small amounts of capital are placed responsibly into millions of productive hands, the impact can become decidedly macro.
Douglas Martin Levermore, MBA, JP, is an independent management consultant and the founding Executive Director of Jamaica’s Public Investment Management Secretariat (PIMSEC)—the government unit established to strengthen project appraisal, fiscal discipline, and oversight of public investment, now known as the Public Investment Appraisal Branch (PIAB) within the Ministry of Finance and the Public Service. He also serves as a FINRA arbitrator and a commissioned Notary Public in the Commonwealth of Virginia. He is available for select international consulting, advisory, keynote speaking, and project-based engagements and may be contacted at [email protected]. These reflections are written with the generous gift of a stranger whose kindness gave him more time—a tribute to the organ donor whose legacy lives on through every word.
Comments