What Jamaica’s new bond coupon will reveal about investor confidence

/ Our Today
administrator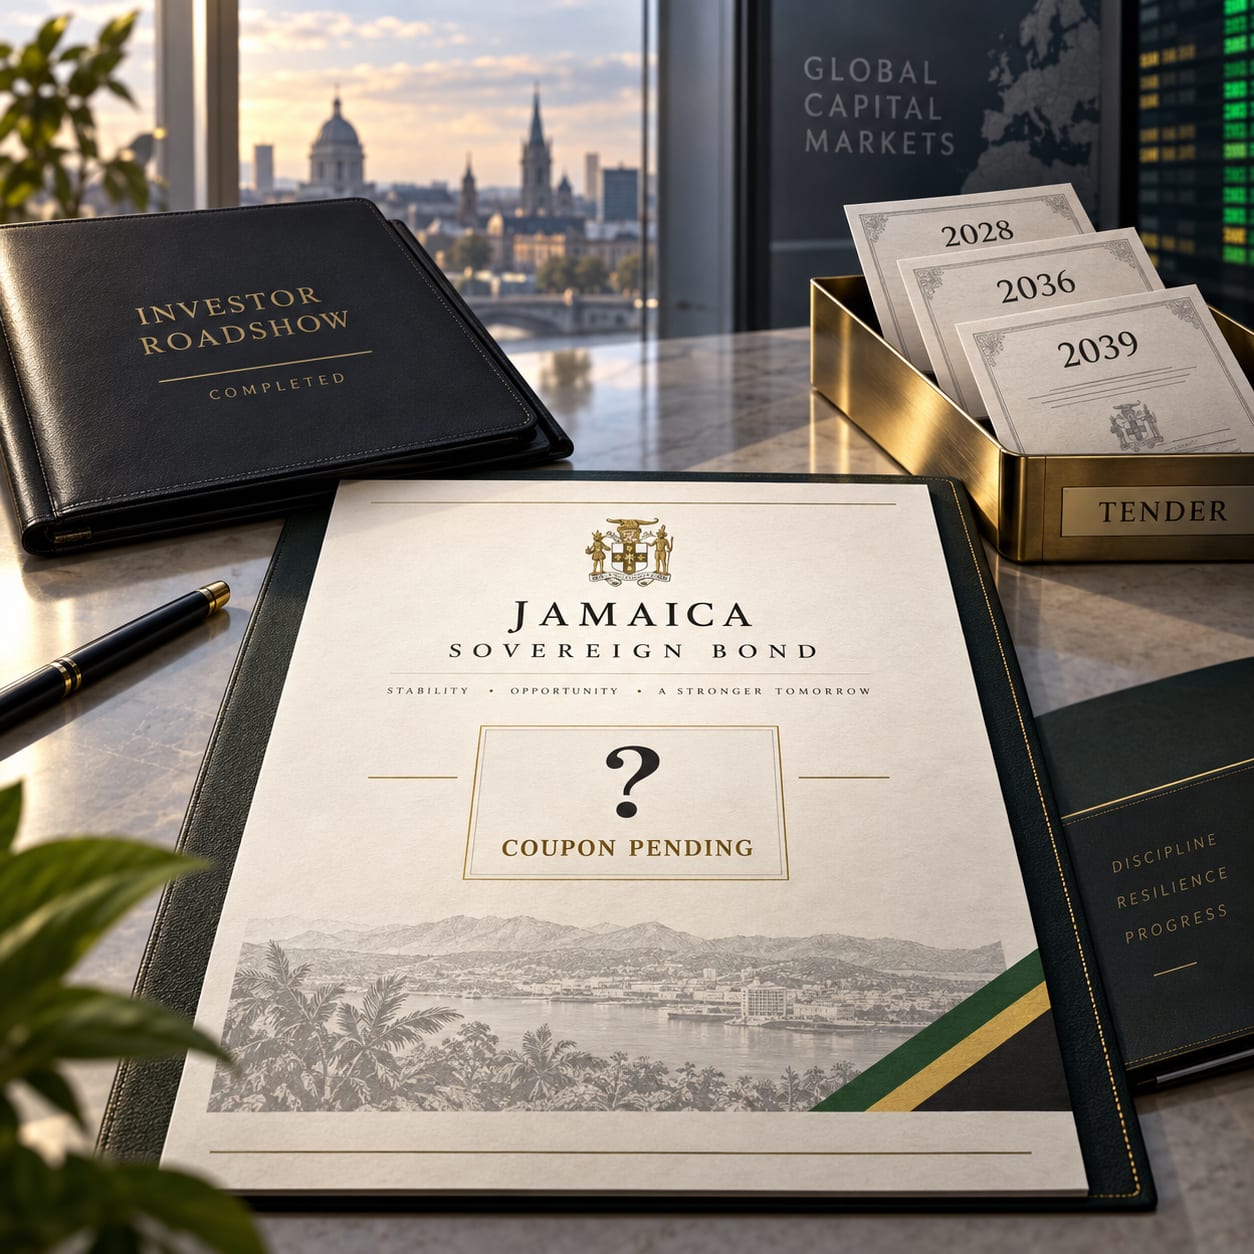
Jamaica’s roadshow for a new international bond has wrapped up, and the tender offer built around it closes today.
The one number that will matter most, the coupon on the new issue, has not been published yet.
That gap is deliberate rather than an oversight. Sovereign borrowers typically disclose final terms only once the order book closes, not while investor meetings are still underway. Investor meetings for the new bond began September 3, with the notes expected to list on the Euro MTF market of the Luxembourg Stock Exchange. Citigroup Global Markets and Scotia Capital are managing both the new issue and the linked buyback of the 2028, 2036 and 2039 notes.
The coupon matters because it is the cleanest available signal of how the market prices Jamaican risk today, months after Hurricane Melissa caused damage equivalent to more than half the island’s annual economic output. Jamaica has not tapped international bond markets in close to three years, which makes this pricing the first fresh data point since the storm.

The backdrop is more favourable than a hurricane-year issuance might suggest. S&P Global Ratings upgraded Jamaica’s long-term sovereign credit rating to ‘BB’ from ‘BB-‘ in September 2025, with a positive outlook, citing a decade of primary fiscal surpluses above 3 per cent of GDP, a record S&P said no other of the 141 sovereigns it rates had matched. Jamaica’s net government debt has fallen from a peak near 145 per cent of GDP to roughly 62 per cent, according to the ratings agency’s commentary at the time. Moody’s has tracked a similar trajectory, moving Jamaica’s rating up through the single-B range over the past decade.

Whether that improvement translates into a materially cheaper coupon depends on what investors demand for taking on a small, tourism-reliant, hurricane-exposed economy. The bond being refinanced most directly, the 6.750 per cent notes due 2028, was priced in calmer conditions years ago. A new coupon that comes in meaningfully below that level would support the government’s case that its credit story has genuinely improved. A coupon that lands close to or above it would suggest investors are still charging a climate-risk premium that the rating upgrades have not fully erased.
There are reasons to expect a reasonably receptive market. Jamaica’s disaster risk toolkit, including catastrophe insurance, is estimated to provide around $660 million in immediate liquidity following Melissa, reducing the government’s need to lean on expensive commercial borrowing for storm recovery. The Bank of Jamaica has also been cutting its policy rate, bringing it to 5.50 per cent by February as inflation eased faster than initially feared after the hurricane. Both factors support the fiscal narrative Jamaica is presenting to bond investors even as debt-to-GDP is projected to tick up before resuming its decline.
The mechanics tie the two transactions together tightly. Jamaica has authorisation to borrow up to $1 billion under the new bond, described by the Gleaner as a ceiling rather than a fixed target, with proceeds going first to fund the buyback and any remainder to the general budget. That means the coupon and the final size of the new issue will jointly determine how much of the $2.33 billion in old debt actually gets retired, and investors watching the pricing will be reading two signals at once: the cost of new borrowing, and the government’s confidence in demand.
Both numbers are due for confirmation around the September 17 settlement date.
Comments